Articles about Retirement

Latest article

Interest rates remain a critical factor in shaping the financial environment. Exerting influence on borrowing costs, investment strategies, and overall economic stability. As we continue into 2024, the repercussions of interest rate fluctuations continue to ripple across various sectors. With significant implications for borrowers and lenders alike. Let's explore how the shifts in interest rates are impacting loan-to-value (LTV) levels and lending patterns in the UK. Explaining the impact of Interest Rates. in this simple, clear educational article from Retirement Solutions.
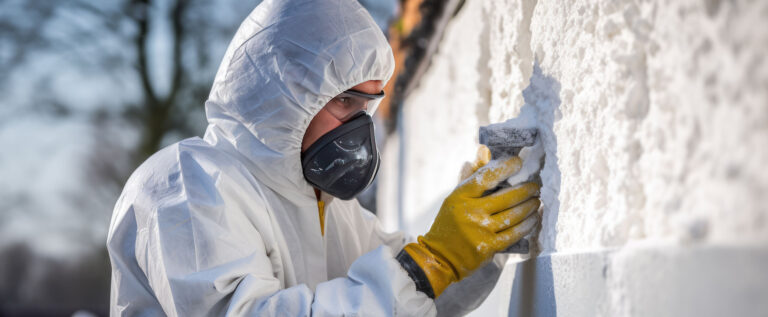
Spray foam insulation has gained popularity as an effective method to improve energy efficiency in homes. However, recent reports suggest that its use can have implications on mortgages, finance, insurance, and equity release. In this article, we delve into the challenges homeowners face when using spray foam insulation in their properties and explore potential solutions. This Retirement Solutions article looks at Spray Foam and Mortgages.
Can I release equity for a home improvements? Yes.  Many people who release equity from their homes do so for home and garden improvements such as refurbishments, extensions, or new furniture. You might choose to use the money released to make your home more accessible if you have mobility requirements – for example, by adding ramps, widening doorways, and installing handrails. Equity release can help you achieve these goals and ensure your home is comfortable and safe in your retirement. Let's look at home improvements.
When homeowners need additional funds, they may explore various financing options. One such option is a second charge mortgage. Providing a way to tap into the equity built up in a property. In this Retirement Solutions article, we'll delve into the concept of second charge mortgages. Exploring what they are, how they work, and the pros and cons associated with this financial solution.
As a member of the Equity Release Council, we only recommend equity release products that meet all the Equity Release Council’s product standards. The Equity Release Council represents the equity release sector and exists to promote high standards of conduct and practice in the provision of and advice on equity release which have consumer safeguards at its heart.
Investing in property has long been a popular avenue for wealth creation, and for many, buy-to-let properties offer an attractive opportunity. Whether they are single occupancy lets, Houses of Multiple Occupancy (HMO), Homes for families or Commercial Units. Buy-to-let mortgages are a specialised financial product designed to facilitate property investment for the purpose of generating rental income. In this Retirement Solutions article, we'll delve into what buy-to-let mortgages are, how they work, and the pros and cons associated with this form of property financing.
The most popular type of equity release plan is a lifetime mortgage. A loan is secured against your home and in return, you can release a tax-free cash lump sum. The amount of tax-free cash you can release is based on your age and the value of your home. Interest is added throughout the lifetime of the loan on a compound basis as typically you will not be required to pay regular monthly repayments. However, you can pay the interest if you want to, the choice is yours. The amount of equity released plus the interest accrued will be repaid when you die or move into long-term care.
A Lifetime Mortgage Drawdown plan is a popular method for homeowners to release equity from their property. This type of mortgage allows homeowners to release equity in amounts over time, starting with an initial release and followed by further releases as and when the homeowner needs additional tax-free cash.
A lifetime mortgage is a type of equity release where a loan is secured against your home based on its value. You own the home and pay the loan back when the property is sold after your death or when you move into long-term care.  A lifetime mortgage is a type of equity release where a loan is secured against your home based on its value. You own the home and pay the loan back when the property is sold after your death or when you move into long-term care. Many homeowners take equity release because they might not have enough savings and need extra money to help with the cost of living. Other homeowners want to enhance their quality of life or help a loved one. Should you decide to proceed with a Lifetime Mortgage, you have a choice about whether to receive your tax-free funds in a lump sum or in stages via drawdown. This article is for information purposes only. Always seek independent financial advice regarding your personal circumstances. Many homeowners take equity release because they might not have enough savings and need extra money to help with the cost of living. Other homeowners want to enhance their quality of life or help a loved one. Should you decide to proceed with a Lifetime Mortgage, you have a choice about whether to receive your tax-free funds in a lump sum or in stages via drawdown. 
As UK retirees consider their financial options, estate planning becomes a critical aspect of ensuring a comfortable retirement. One avenue that has gained prominence is equity release, specifically through lifetime mortgages. In this article, we'll explore the pros and cons of using a lifetime mortgage as part of your estate planning strategy. Let's look at estate planning with a lifetime mortgage.
When choosing what to do with their legacies, or gifting funds to children and grandchildren. The Bank of Mum and Dad is changing as Facts from the Institute of Fiscal Studies Depict.   Around 5% adults received a substantial gist and 2% a sizeable loan from friends or family. At some stage in their 20s and 30s adults have received at least one transfer.

Start Your Equity Release Journey Today with a Free Valuation!

Discover how much equity your home could
unlock – it all begins with a quick and easy property valuation.

Equity release could help you access the cash tied up in your home for a more comfortable retirement. The first step? Knowing how much your property is worth. Get your free, no-obligation
valuation now.

Powered by
Loader