
Reviewed 24 September 2026
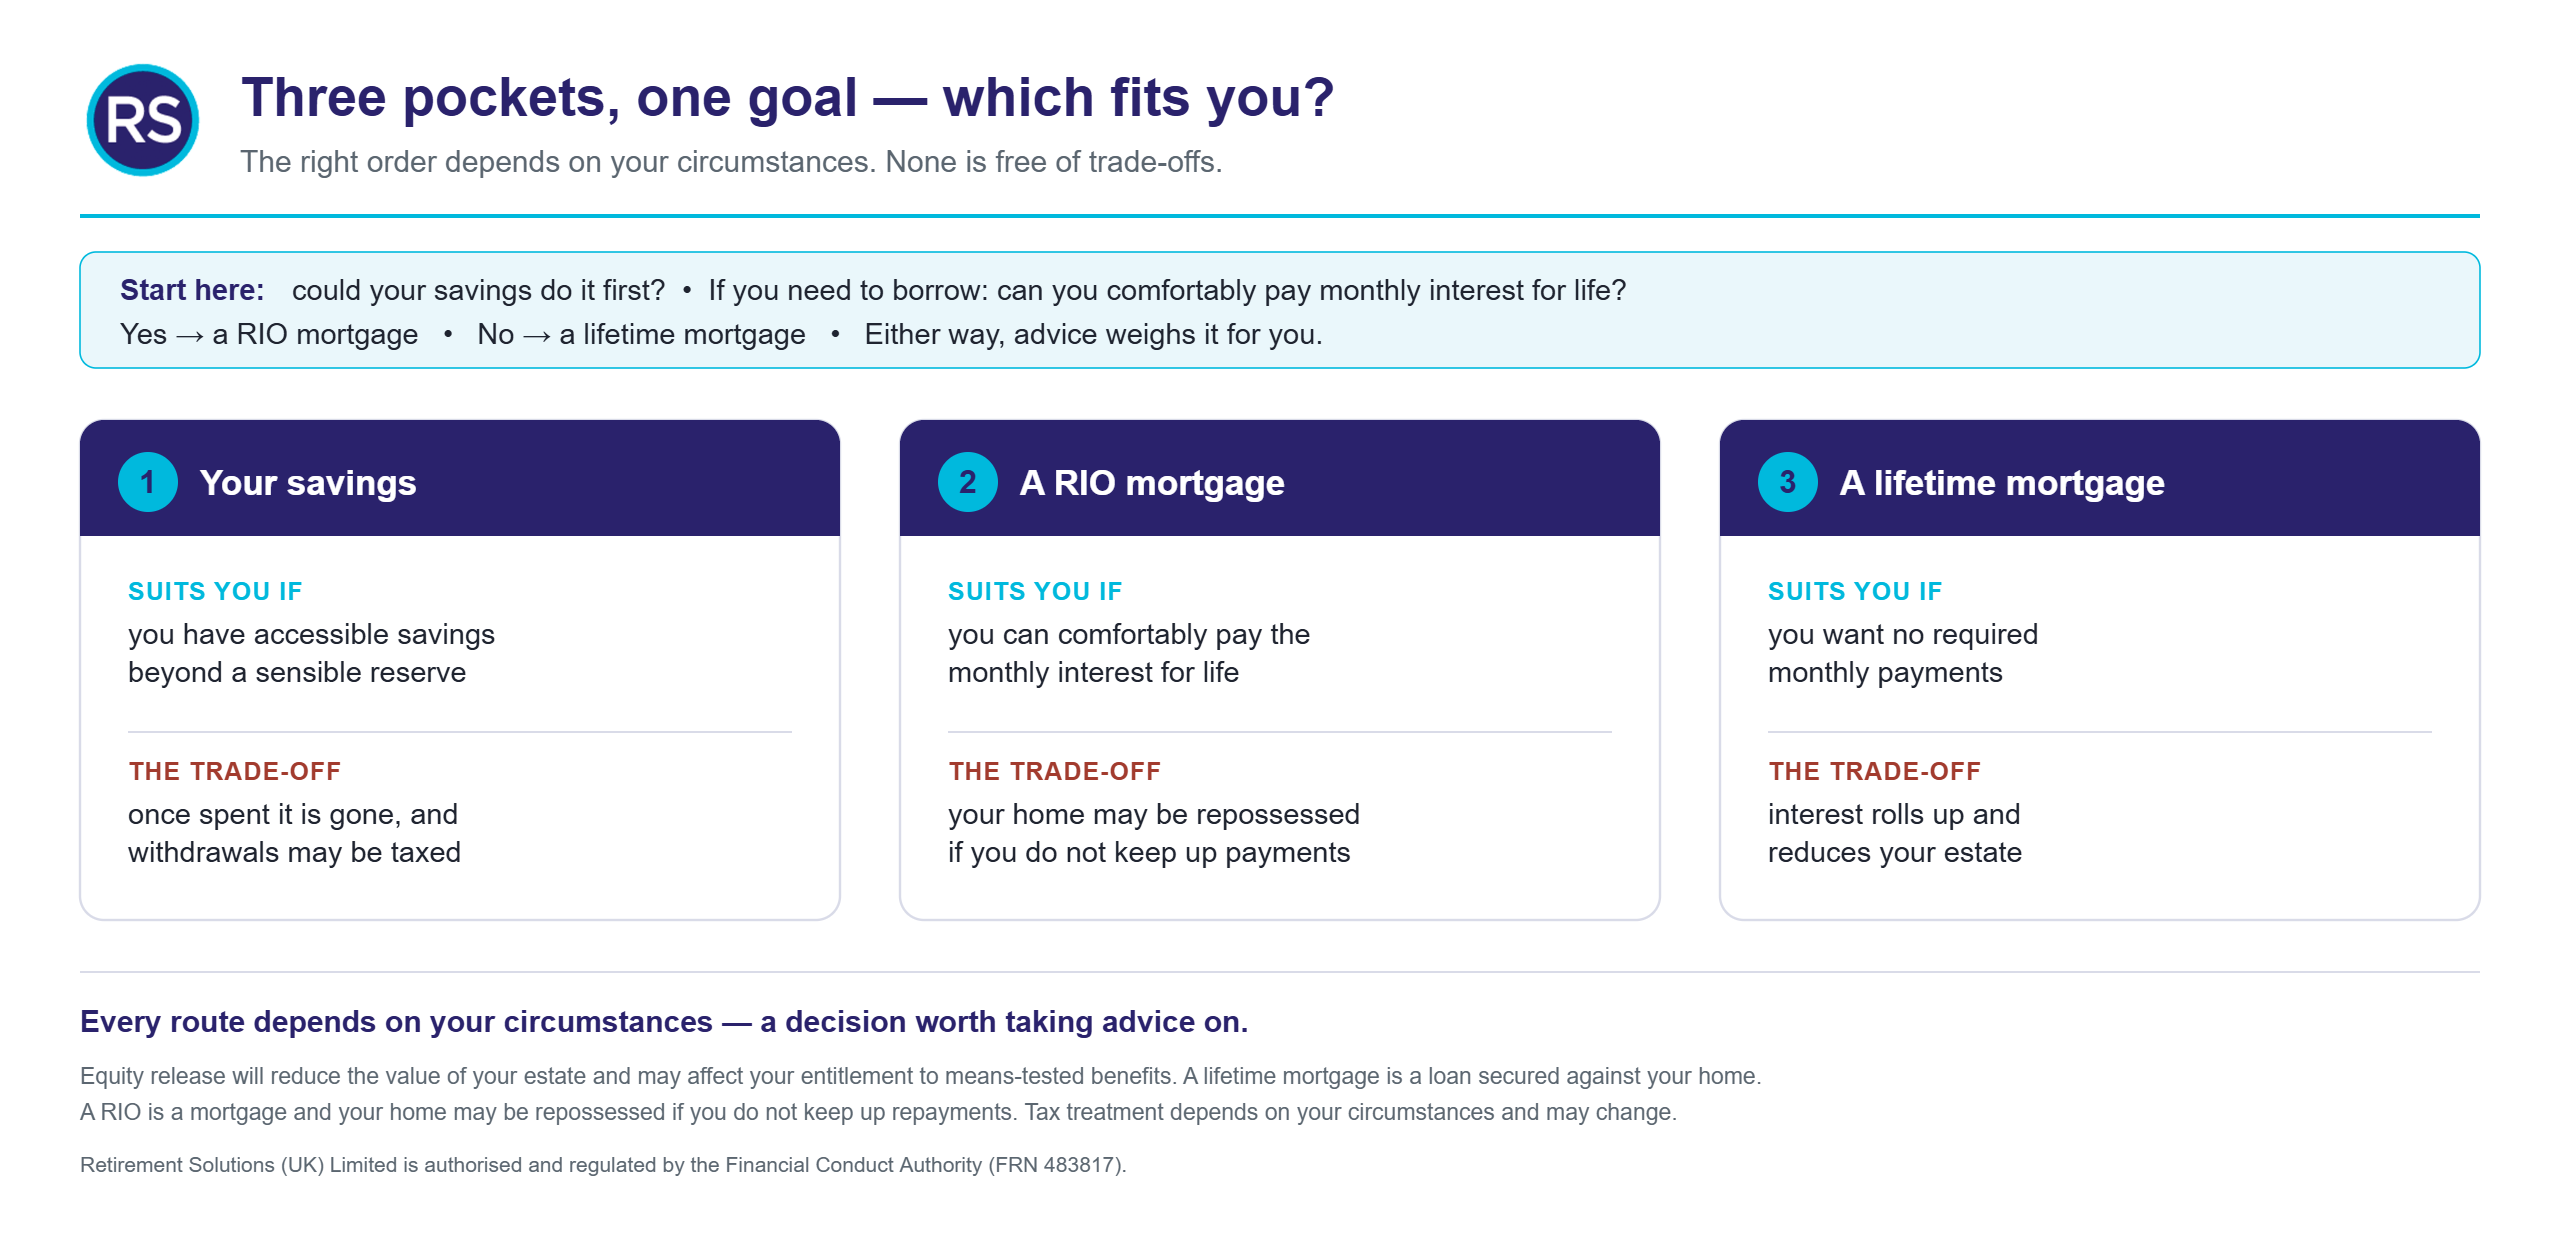
Three pockets can fund the same goal: accessible savings (usually the cheapest), a retirement interest-only mortgage if you can comfortably pay the monthly interest, and a lifetime mortgage if you want no required monthly commitment. The right order depends on your income, your tax position, and what you want to leave behind — which is why it is a decision worth taking advice on.
In short: none is free of trade-offs — savings once spent are gone and may be taxed; a RIO needs monthly interest you can afford for life; a lifetime mortgage rolls up interest that reduces your estate. Which fits depends on your circumstances.

Pocket one: savings and investments
Money you already hold is usually the cheapest money you can spend — no interest, no fees, no charge on your home. If you have accessible savings beyond a sensible emergency reserve, using them generally comes first. The exceptions are where the savings are doing important work — income, or planned costs — or where the tax consequences of a withdrawal bite. That is where advice tailored to your circumstances matters.
A note on pensions and Inheritance Tax — as at 24 September 2026
From 6 April 2027, under the Finance Act 2026, most unused pension funds and pension death benefits are due to count within your estate for Inheritance Tax. For some families that changes the old “spend everything else before the pension” order — and it makes personal advice on the order of withdrawals more valuable, not less.
This is general information, not tax advice: tax depends on your circumstances and the rules can change. (Source: HMRC technical note on Inheritance Tax on pensions; Finance Act 2026.)
Pocket two: a retirement interest-only (RIO) mortgage
A RIO is a mortgage where you pay the interest every month, and the capital is repaid when the home is eventually sold. Because the interest is paid as you go, the balance does not grow — which protects your estate. But it requires income you can comfortably sustain for life, and, like any mortgage, your home may be repossessed if you do not keep up the payments. If a RIO suits you better than a lifetime mortgage, we will tell you — even if that means pointing you to the right route for it.
Pocket three: a lifetime mortgage
A lifetime mortgage has no required monthly repayments on most plans, though product terms vary, with the interest rolling up instead. It compounds against your estate over time. It suits people whose wealth is in the home rather than in income, who want the certainty that no monthly bill arrives, and who have weighed the compounding cost against the estate with their family in the picture. Optional repayments can bridge the two worlds: pay when it suits you, stop when it does not.
The right order, usually
For most people: accessible savings first, with tax advice where pensions are involved; then a RIO, if monthly payments are comfortably affordable and protecting the estate matters most; then a lifetime mortgage, where avoiding a required monthly payment matters most. “Usually” is doing real work in that sentence — which is why the right order depends on your circumstances, and is a decision worth taking advice on.
We advise on the mortgage and equity release routes, not on tax. Where pensions, savings or Inheritance Tax are involved, a qualified tax or financial adviser should guide the order of withdrawals.
Risk warning. Equity release will reduce the value of your estate and may affect your entitlement to means-tested benefits. A lifetime mortgage is a loan secured against your home. To understand the features and risks, ask for a personalised illustration.
If you would like help weighing the routes, a good adviser will compare them with you — including concluding that using your own savings, or doing nothing, is the better answer. Our first conversation costs nothing and carries no obligation. Speak to an adviser.
If a lifetime mortgage looks like your route, our free calculator gives an indication of what might be possible, in a couple of minutes and with no obligation — a guide, not a formal figure.

Frequently asked questions
Is a RIO mortgage better than a lifetime mortgage?
It can be, if you can comfortably afford the monthly interest for life. Because you pay the interest as you go, a RIO keeps the balance from growing, which protects your estate. A lifetime mortgage has no required monthly payments but the interest rolls up and compounds. Which suits you depends on your income and what you want to leave behind — and, like any mortgage, a RIO can be repossessed if you do not keep up payments.
Should I use my savings or take equity release?
It depends on your circumstances. Money you already hold is usually the cheapest to spend, so for some people using accessible savings beyond a sensible reserve could be a more sensible route than borrowing. Sometimes, though, the savings are doing important work, or the tax consequences of a withdrawal bite, especially where pensions are involved. A qualified adviser can help you weigh the order for your situation.
Will the April 2027 pension changes affect equity release?
Not directly, but they may change the order in which it makes sense to draw on different pockets. From 6 April 2027, most unused pension funds are due to count within your estate for Inheritance Tax, which can make the order of withdrawals more important. This is general information, not tax advice — speak to a qualified adviser about your circumstances.
Related guides
- How equity release works
- Equity release or downsizing?
- How our advice works and what we charge
- Ten questions to ask any adviser
This page was last reviewed and dated 24 September 2026. The April 2027 tax note is re-verified on each update.
Retirement Solutions (UK) Limited is authorised and regulated by the Financial Conduct Authority (FRN 483817). Registered in England and Wales, company number 06437737. Registered office: Metropolitan House, Station Road, Cheadle Hulme, Cheshire, SK8 7AZ.


